
Lesson 14 of 16 · Page 5 of 7
Cover the gap with as little as it takes
Lifetime income can cover essential spending. Find the gap first, then use as little of the client's money as covers it.
Do it in Genius
Income rider calculator Solve for: Premium Desired Monthly Income
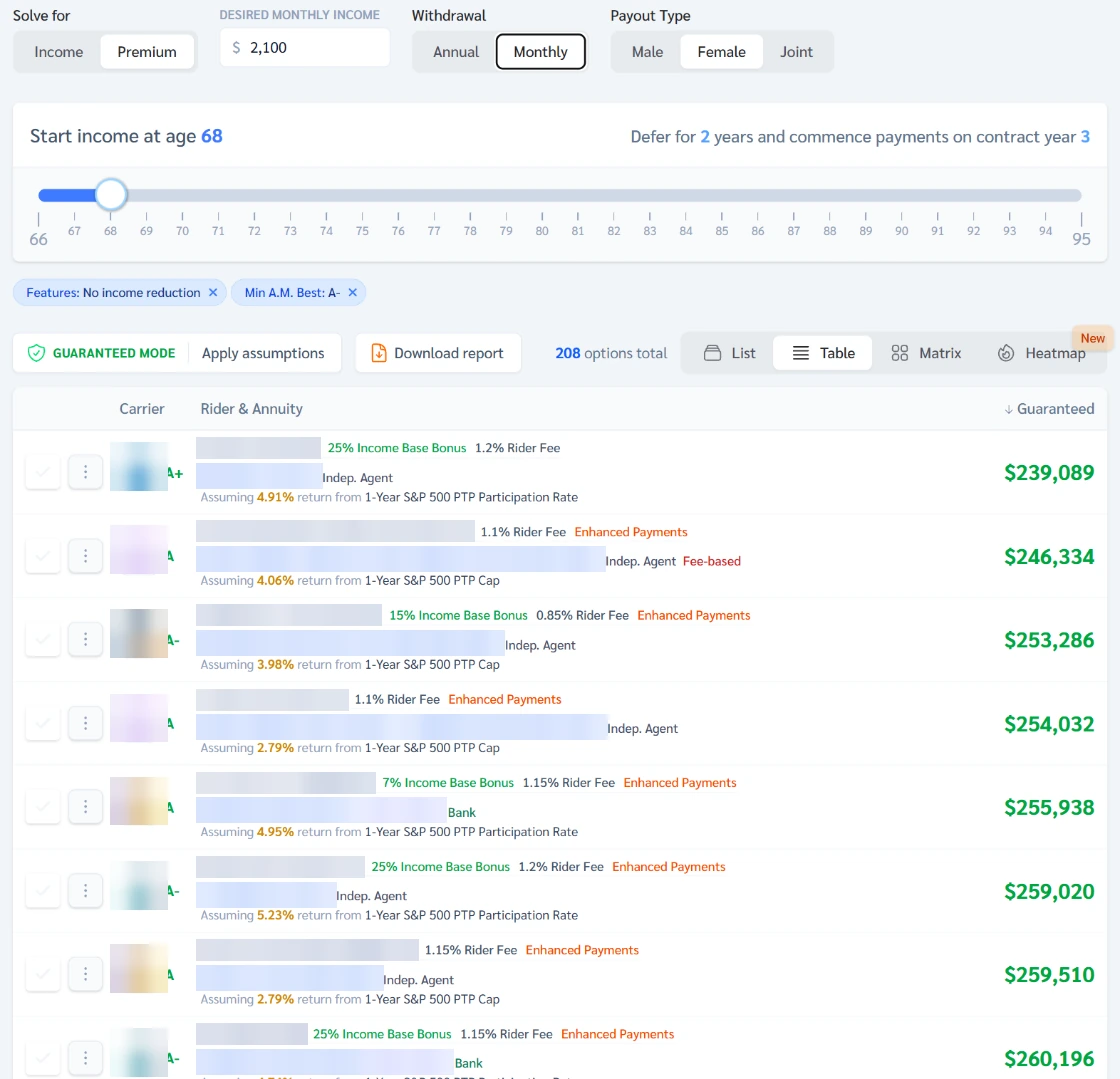
Practice Client, 12 Nov 2026: for an example $2,100 monthly gap from 68, the first sellable row needs $251,497. She has $150,000.
Rates change every day, so yours will differ.
Open Income rider calculator in Genius (opens the app in a new tab)In the app: Calculators → Income rider calculator
 (opens full size in a new tab)
-
1.
Find the gap: essential spending after tax minus steady income (Social Security, pensions). Open Retirement in the left card, or ask GrantAI.
Type essential spending only. GrantAI may size its answer on a Fee-based row, so on commission use your own rows.
-
2.
In Income rider calculator, set Solve for to Premium. Set Withdrawal to Monthly and type the monthly gap in Desired Monthly Income.
Monthly gap in, premium out: the first sellable row needs $251,497. Note: what it takes, what they have, how close.
-
3.
Read the premium each of the top rows needs. Then set Solve for back to Income to see what $150,000 buys.
The first seven rows need $246,334 to $257,300. Row 1 is Fee-based. On row 2, $150,000 pays $1,253 a month.
-
4.
Is the $2,100 firm? If the premium it needs is more than they have, cover part. The client decides whether to add money.
Premium above a product's maximum? Annuity info, Purchase shows the limit. Above it, ask the insurer before you quote.