
Lesson 14 of 16 · Page 4 of 7
Zero growth and the fee
A client sees the account hit $0 and fears a mistake. Run it with no growth: the account ends, but income goes on under the rider's rules.
Do it in Genius
Income rider calculator row ⋮ Illustrate Genius Illustration
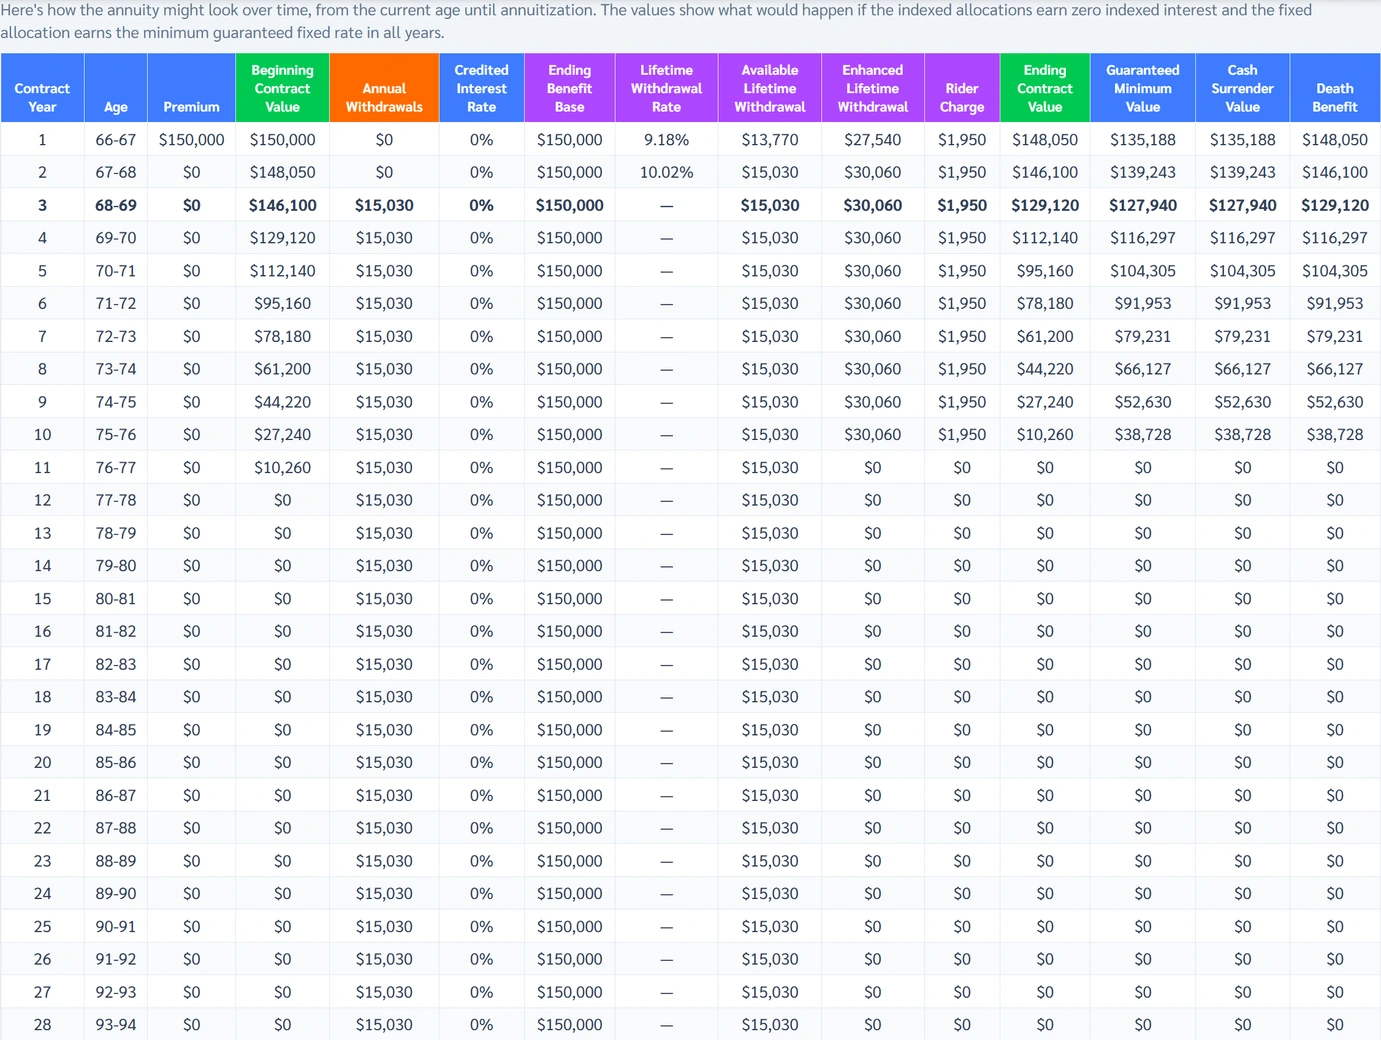
Practice Client, 12 Nov 2026: at 0% growth the account is $0 by age 77. The table still lists $15,030 a year to age 95.
Rates change every day, so yours will differ.
Open Income rider calculator in Genius (opens the app in a new tab)In the app: Calculators → Income rider calculator
 (opens full size in a new tab)
-
1.
Open Deferral snapshot (How long to defer?) on your first sellable row. Copy Benefit Base, Withdrawal Percentage and start age into the tool below.
12 Nov, first sellable row: Benefit Base $150,000, Withdrawal Percentage 10.02%, start age 68.
-
2.
Click Illustrate. Type the contract value as income starts: Carrier Illustration if any, else Beginning Contract Value in Genius Illustration.
12 Nov: $146,100 at 68, not the premium. Ending Contract Value, $129,120, is after the first income and fee.
-
3.
Click the three dots, Annuity info, Riders. Find Fee based on benefit base and type that fee and what it is charged on.
In the Practice Client's 12 Nov illustration the account shrinks $1,950 a year before income: 1.3% of a $150,000 base.
-
4.
Read Year the account is gone and Fee's share of the account, first year against last full year.
12 Nov: year 9, gone by 77. Income to 95, when the contract annuitizes. Ask what the insurer pays after.
Sources
- Annuities Genius help: Deferral Snapshot
- Annuities Genius help: What Is the Performance Analyzer
- Annuities Genius help: Income Rider Calculator Report
- NAIC: Buyer's Guide for Deferred Annuities
- Annuities Genius help: Income Rider Calculator
- Annuities Genius help: Credits, Plans & Pricing
- Annuities Genius app, checked 3, 10 and 12 Nov 2026