
Lesson 8 of 14 · Part 4 of 6
Replace or keep? Count the exit and the gain
Replace only when the client clearly comes out ahead after every cost.
Do it in Genius
All cases your client GrantAI More Annuity replacement Give-Up vs. Gain
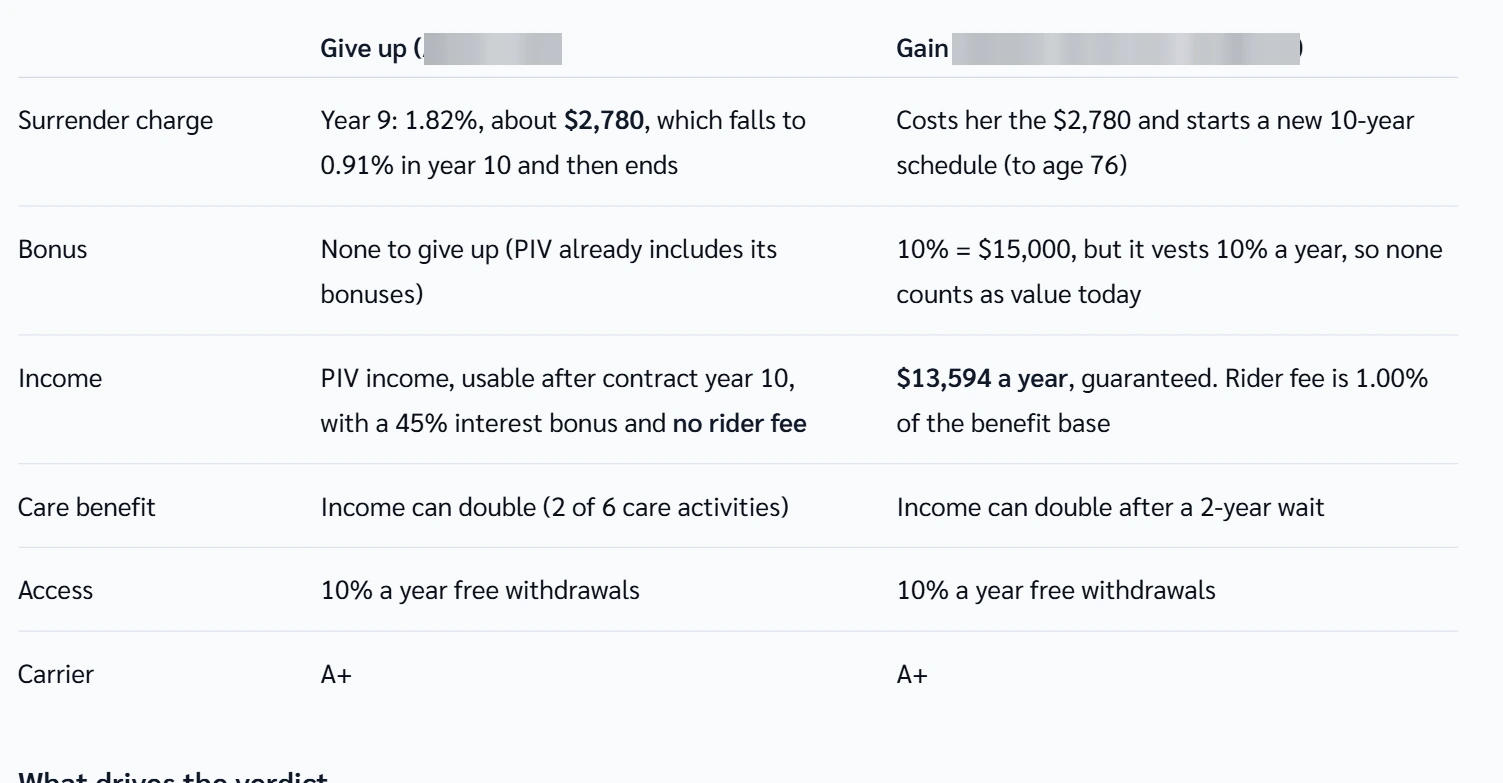
Practice Client, 3 Nov 2026: GrantAI says replacing is not defensible. Its Give-Up vs. Gain table puts the penalty at about $2,780.
Rates change every day, so yours will differ.
Open your clients in Genius (opens the app in a new tab)In the app: CRM → All cases
 (opens full size in a new tab)
-
1.
Write old and new side by side: income, account value, surrender value, schedule, rate, rider cost, death benefit.
GrantAI's Give-Up vs. Gain table starts it. Use your state's form too.
-
2.
Account value minus surrender value is the dollar cost of leaving today. Ask for dollars: a percent can hide the MVA.
The benchmark used the original premium. A replacement quote runs on the surrender value you can actually move.
-
3.
Does the new bonus cover the charge? Count a vested bonus on the account value, not one on the income base.
- 1035 exchange
- A qualifying annuity-for-annuity swap, insurer to insurer. It defers tax on the gain, but cash paid to the owner can make it taxable. State replacement rules still apply.
- Trustee-to-trustee transfer
- IRA money moves straight between companies. A 1035 exchange is for non-qualified money.
Practice Client: a new 10-year schedule, to about age 76. The $15,000 bonus vests 10% a year: none counts today.
-
4.
No clear gain? Keep it, or wait for the charge to step down. Offer a yearly review and write down why.
GrantAI said look again after year 10. Year 9 costs about $2,780. By year 10 the charge is 0.91%.
Sources
- Annuities Genius help: VA to FIA Transition
- 26 U.S.C. 1035: exchanges of annuities
- NAIC Model 613: life insurance and annuities replacement
- NAIC Model 275: suitability in annuity transactions
- FINRA Rule 2330: variable annuity exchanges
- FINRA Rule 1220: registration categories
- NAIC Model 245: annuity disclosure
- NAIC: Buyer's Guide for Deferred Annuities
- Annuities Genius app, checked 3 Nov 2026