
Lesson 8 of 14 · Part 2 of 6
Benchmark it: still competitive today?
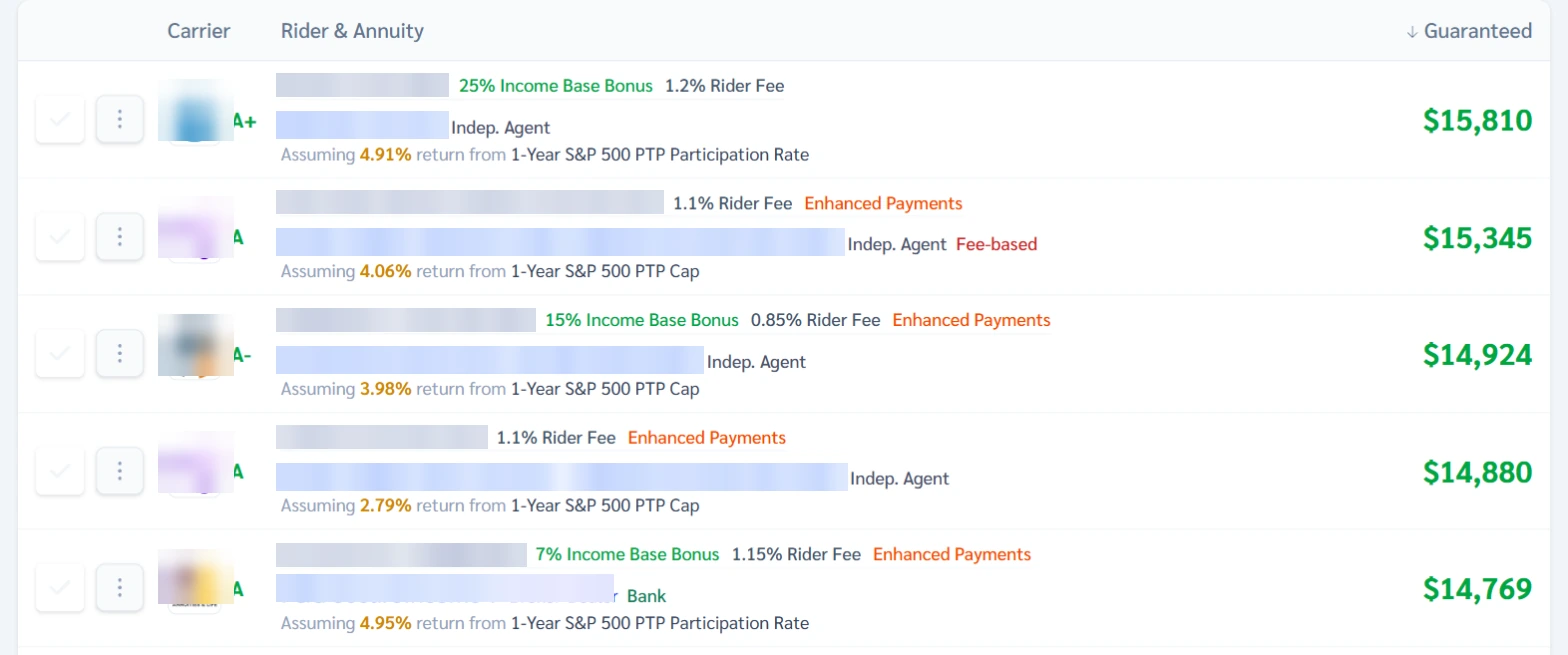
For an income contract, run the client's facts as if buying today, on the original premium. The ranked list shows where its income stands.
Do it in Genius
Income rider calculator Rider features: No income reduction Payout Type Start income at age
Practice Client, 3 Nov 2026: with start age 68 and No income reduction on, row one pays $15,810 a year. Row three pays $14,924.
Rates change every day, so yours will differ.
Open Income rider calculator in Genius (opens the app in a new tab)In the app: Calculators → Income rider calculator
 (opens full size in a new tab)
-
1.
Open Income rider calculator. Match Rider features, Payout Type and Start income at age to the old contract.
Original premium shows how the old deal ranks. The next parts run the new quote on the surrender value. Set it on the client: pencil, Premium Amount.
-
2.
Find the client's current yearly income in the ranked list. Near the top? Say so plainly. On commission? Skip Fee-based rows.
Row two for the Practice Client is Fee-based, so a commission agent skips it. Yours will differ. Calculator figures: confirm them in the illustration.
-
3.
Ask the carrier for an in-force illustration at zero growth. Walk its columns: account value, withdrawals, income base.
- In-force illustration
- An illustration of a contract the client already owns, run by the insurer from today's values.
Practice on a new quote: row one, ⋮, Illustrate, Carrier Illustration. At 0% growth its account is $0 at 76.
-
4.
Bought lately and it fits their goal? Say so first, and name the free-look days left.
Free-look days differ by state and contract. Read them from the contract or ask the carrier.
Sources
- Annuities Genius help: Income Rider Calculator
- Annuities Genius help: Deferral Snapshot
- NAIC Model 275: suitability in annuity transactions
- NAIC Model 613: life insurance and annuities replacement
- NAIC: Buyer's Guide for Deferred Annuities
- NAIC Model 245: annuity disclosure
- Annuities Genius app, checked 3 Nov 2026