
Lesson 2 of 14 · Part 5 of 5
Keep annuities out of the Medicare appointment, then prepare the separate talk
Keep annuities out of every Medicare appointment, even if the client asks. The income talk is a separate contact, set up outside the appointment.
Do it in Genius
All cases your client GrantAI More Roth conversion strategy
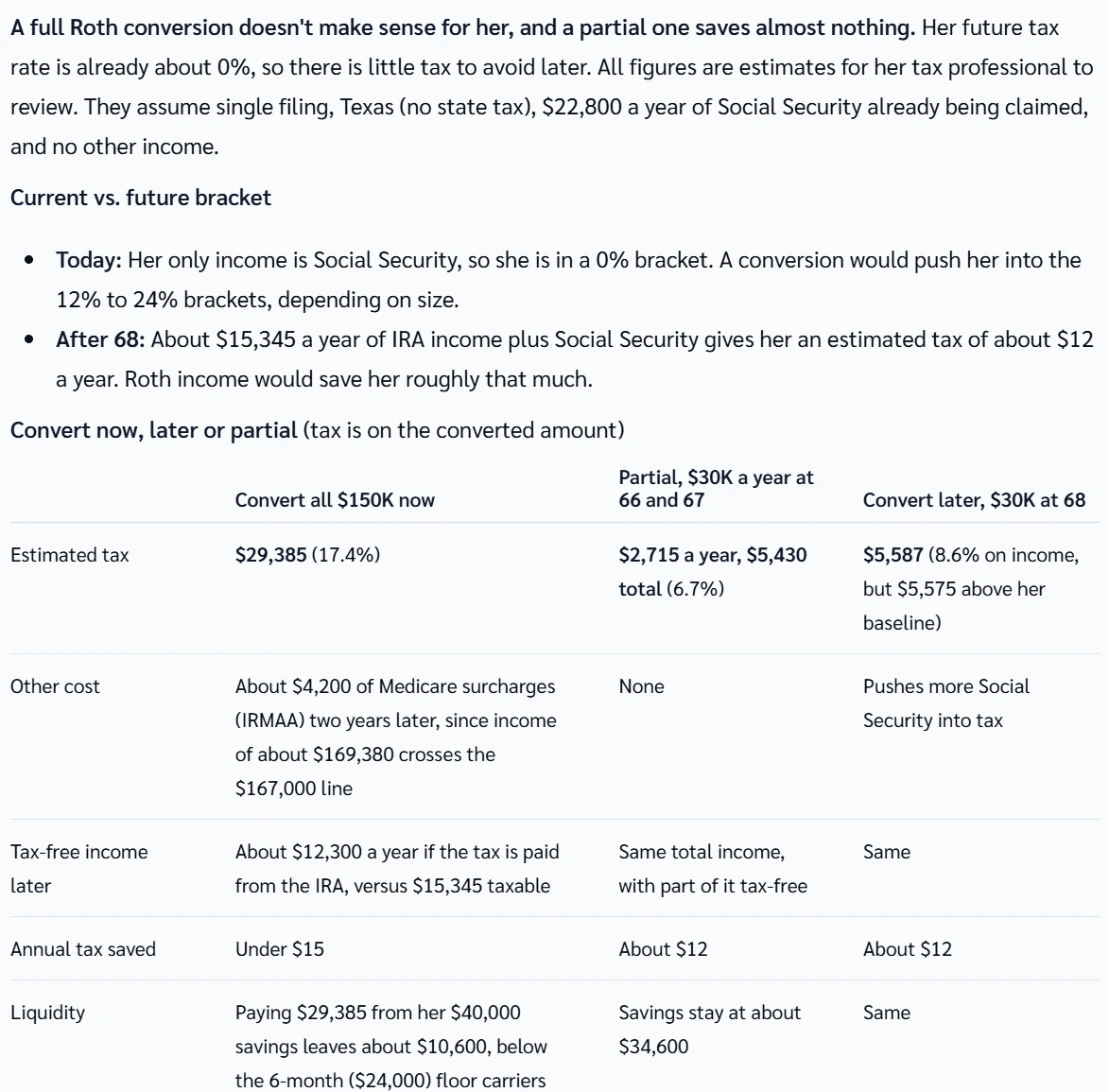
Practice Client, 3 Nov 2026: Roth conversion strategy compares converting now or later. GrantAI said a full conversion made no sense for her.
Open your clients in Genius (opens the app in a new tab)In the app: CRM → All cases
 (opens full size in a new tab)
-
1.
In any Medicare appointment, never raise annuities, even if the client asks. For Medicare Advantage and Part D, federal rules bar it.
If asked, say it is a separate topic for another day. Genius won't stop you. For other Medicare talks, check your IMO's rules.
-
2.
Asked about a higher Part B premium? Answer it as a Medicare question: check whether it is IRMAA, the income surcharge, and stop there.
- IRMAA
- An extra Part B and D premium for higher incomes. It is usually set from the tax return of two years before.
For the separate talk, GrantAI's Financial strategy offers Tax-Bracket Planning and RMD Planning.
-
3.
Traditional IRA money generally faces required withdrawals (RMDs). A longevity annuity (QLAC) can stay out of the RMD balance until it starts.
- RMD
- Required minimum distribution: the least an owner takes out each year. A Roth IRA owner has none. Beneficiaries face rules after death.
- QLAC
- A longevity annuity that meets Treasury rules. Its value can be left out of the RMD balance until payments begin.
For the separate talk: they start at 73 if born 1951 to 1959, at 75 if born 1960 or later.
-
4.
To prepare, run Roth conversion strategy from More on the client. Read Estimated tax and Other cost. Not every client needs it.
- Roth conversion
- Moving money from a traditional IRA to a Roth IRA. The moved amount is taxed that year. Later withdrawals can be tax-free under the rules.
GrantAI estimates about $4,200 of Medicare surcharges later for a full conversion. It assumed $1,900 a month of Social Security, already claimed: a figure typed for this example. Use your own client's facts.
Sources
- Annuities Genius app, checked 3 Nov 2026
- SSA: Medicare premiums for higher incomes (IRMAA)
- SSA POMS HI 01101.010: how IRMAA is set
- IRS: Required minimum distributions
- IRS Publication 590-B: IRA distributions
- Treasury rule: a QLAC is left out of the RMD balance, 26 CFR 1.401(a)(9)-5(b)(4)
- Medicare Advantage rule: no annuity marketing in a personal marketing appointment, 42 CFR 422.2264(c)(3)(iii)(C)
- Part D rule: no annuity marketing in a personal marketing appointment, 42 CFR 423.2264(c)(3)(iii)(C)