
Lesson 9 of 14 · Part 3 of 4
Show the options, name the costs, ask what they dislike
Show the problem, then up to three options. Explain one in order, with its costs. Then ask what is wrong with it.
Do it in Genius
All cases your client Calculators Simulator Add Scenario Lifetime Income
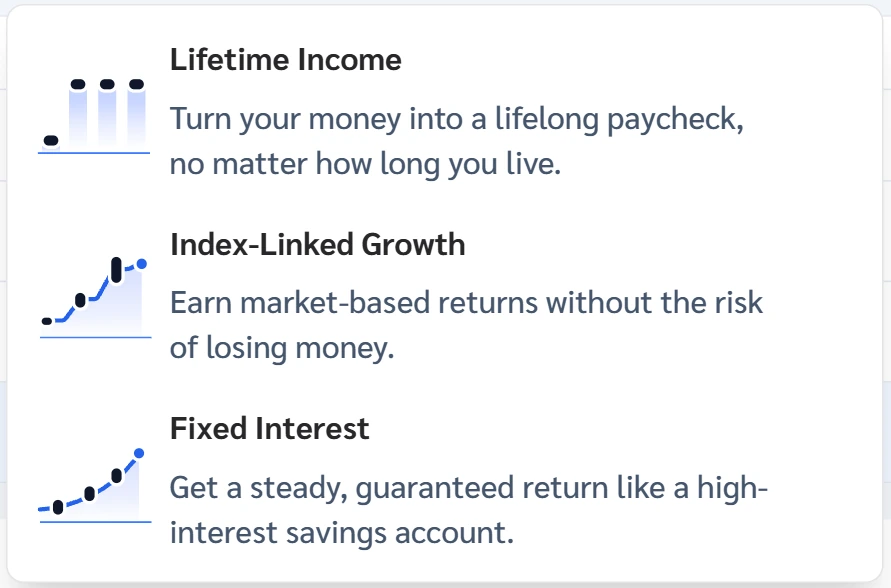
Practice Client, 3 Nov 2026: Add Scenario offers Lifetime Income, Index-Linked Growth and Fixed Interest. Lifetime Income pays about $284,580 to age 86.
Rates change every day, so yours will differ.
Open your clients in Genius (opens the app in a new tab)In the app: CRM → All cases
 (opens full size in a new tab)
-
1.
Show a market path next to an annuity path: Calculators, Simulator, Add Scenario, Lifetime Income. Click Simulate on a row.
In this illustration the account runs out at 80. The rider can keep paying if its rules are followed.
-
2.
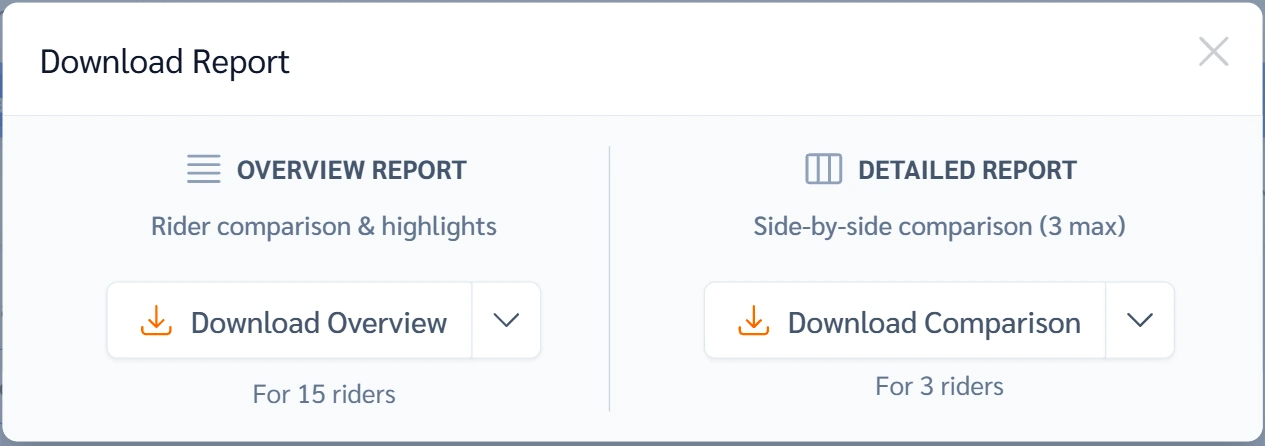
Show up to three options: the Navigator cards, or Download report in Income rider calculator, then Download Comparison (3 max).
Say which you would pick and which pays you more: Show commission in Annuity info. A downloaded comparison is sales material: check it with your IMO and carrier before you hand it over.
 (opens full size in a new tab)
-
3.
Explain your pick from its Navigator card. Fixed part first: income and fee. Then the index part. Ask "Clear?" after each.
- Index part
- Interest the account earns by following an index. A cap, spread or participation rate sets how much of the gain is credited.
First card's costs: Rider Fee 1.2% (about $2,600 a year, can reach 2.50%), Surrender Length 10 yrs, Free Withdrawal 10%.
-
4.
Ask: "What fits what you want, and what does not?" Stay quiet, then save the answer in the client's note.
Ask which option is off the table, then what holds them back.
Sources
- NAIC Model 275: suitability in annuity transactions
- NAIC Model 570: advertisements of annuities
- Investor.gov: annuities
- NAIC: Buyer's Guide for Deferred Annuities
- Annuities Genius help: Cap, Spread and Participation Rate
- Annuities Genius help: I Have a Client, What Next?
- Annuities Genius help: The Retirement Simulator
- Annuities Genius help: Income Rider Calculator Report
- Annuities Genius app, checked 3 Nov 2026