
Lesson 5 of 14 · Part 3 of 10
Zero growth and the fee
A client sees the account hit $0 and fears a mistake. Run it with no growth: the account ends, but income goes on under the rider's rules.
Do it in Genius
Income rider calculator row ⋮ Illustrate Carrier Illustration
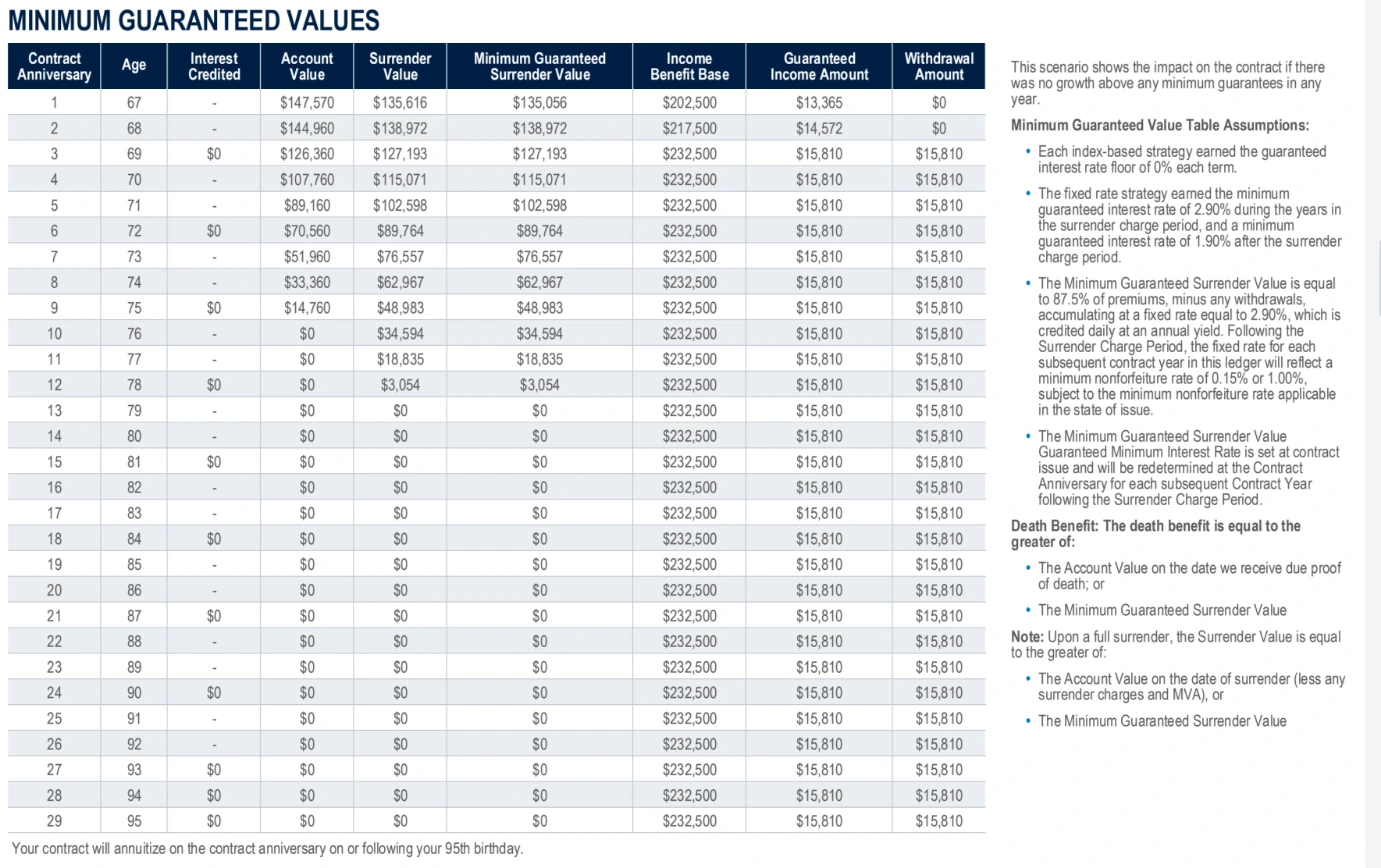
Practice Client, 3 Nov 2026: at 0% growth the account is $0 at age 76. The table still lists $15,810 a year to age 95.
Rates change every day, so yours will differ.
Open Income rider calculator in Genius (opens the app in a new tab)In the app: Calculators → Income rider calculator
 (opens full size in a new tab)
-
1.
Open Deferral snapshot on your top row. Copy Benefit Base and Withdrawal Percentage into the tool below.
In the top row's Genius Illustration, from age 69: base $232,500, payout 6.80%.
-
2.
Click Illustrate, then open Carrier Illustration and its minimum values table. Type the Account Value for the year income starts.
Use the contract value, not the premium or the hypothetical.
-
3.
Click the three dots, Annuity info, Riders. Find Fee based on benefit base and type that fee and what it is charged on.
In the Practice Client's illustration the account shrinks about $2,600 a year before income: 1.2% of a $217,500 base.
-
4.
Read Year the account is gone and Fee's share of the account, first year against last full year.
Illustration: account $0 at 76. The table stops at 95. Its footnote says the contract annuitizes then, so read what the insurer pays afterward. Growth is not the point.
Sources
- Annuities Genius help: Deferral Snapshot
- Annuities Genius help: What Is the Performance Analyzer
- Annuities Genius help: Income Rider Calculator Report
- NAIC: Buyer's Guide for Deferred Annuities
- Annuities Genius help: Income Rider Calculator
- Annuities Genius help: Credits, Plans & Pricing
- Annuities Genius app, checked 3 Nov 2026