
Lesson 1 of 14 · Part 3 of 4
Check the answer before you show it
Check every row before it goes near a client. Read the channel, the Fee-based tag, any income drop and the fee.
Do it in Genius
Income rider calculator Rider features: No income reduction row
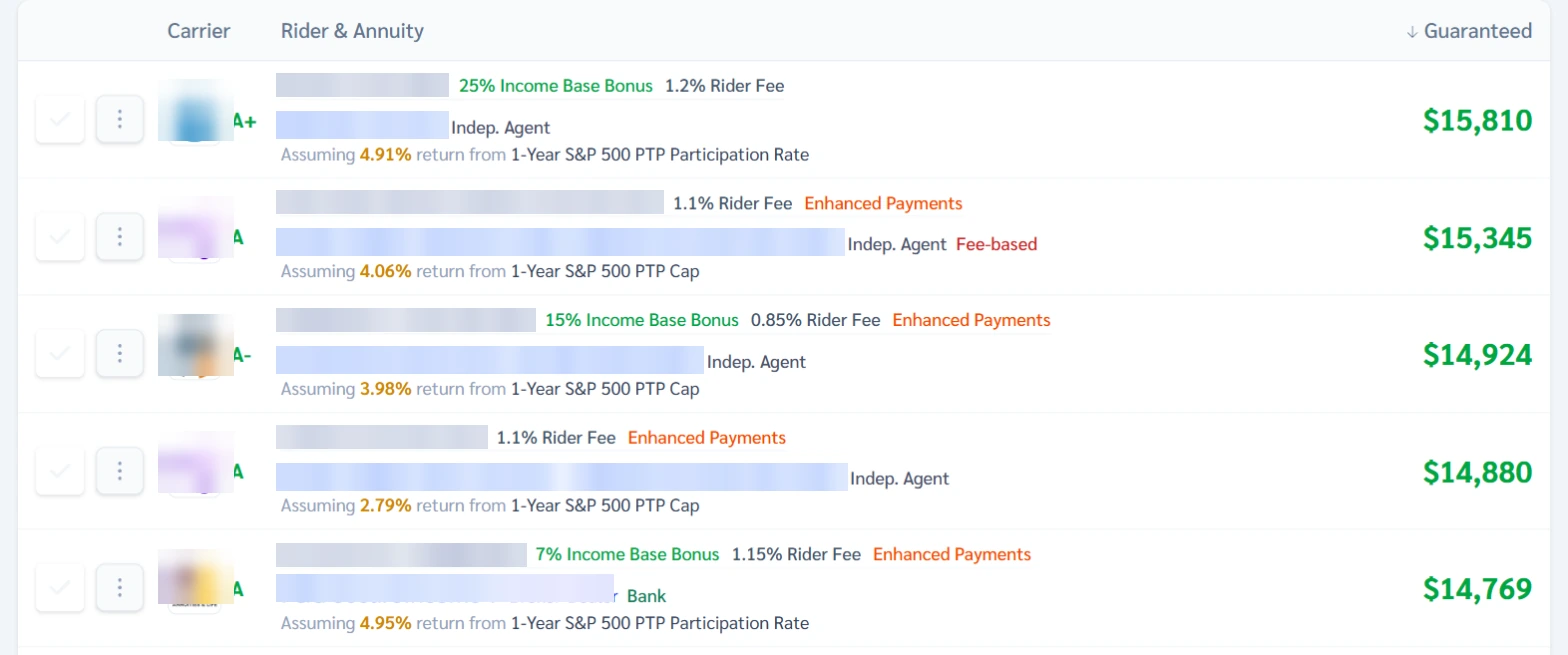
Practice Client, 3 Nov 2026: with No income reduction on, row two pays $15,345 a year. Tags: Indep. Agent, Fee-based, 1.1% Rider Fee.
Rates change every day, so yours will differ.
Open Income rider calculator in Genius (opens the app in a new tab)In the app: Calculators → Income rider calculator
 (opens full size in a new tab)
-
1.
Open Income rider calculator. Keep Start income at age on 68 and No income reduction on. Find GrantAI's $15,345 row.
It opens with your client filled in. Filters can stay on from your last visit. The pick is row two.
-
2.
Read the row's tags: sales channel, Fee-based (sold for an advice fee) and Rider Fee. The $15,345 row says Indep. Agent, Fee-based, 1.1%.
On commission, skip Fee-based rows. An orange Enhanced Payments tag marks the care doubler: the link under the next step explains it. To list only your own insurers, ask your admin or support.
-
3.
Look at the row above it. It lacks the Fee-based tag: 1.2% Rider Fee, 25% Income Base Bonus, $15,810 a year, shown from 68.
The carrier's illustration first pays that $15,810 at 69, not 68. Check the year before you quote.
-
4.
A row tagged Income Can Decrease pays less from a later age. From age under the income shows when and how much.
- Income Can Decrease
- A tag on a row whose yearly income steps down at a later age.
No income reduction hides these rows. The full comparison is in Run every option.