
Lesson 6 of 14 · Part 1 of 6
A fixed rate for a set term: the MYGA
A MYGA is a fixed annuity that pays one stated rate for a set term. Your client will compare it with a CD, so compare more than the rate.
Do it in Genius
MYGAs Term Earnings Withdrawal
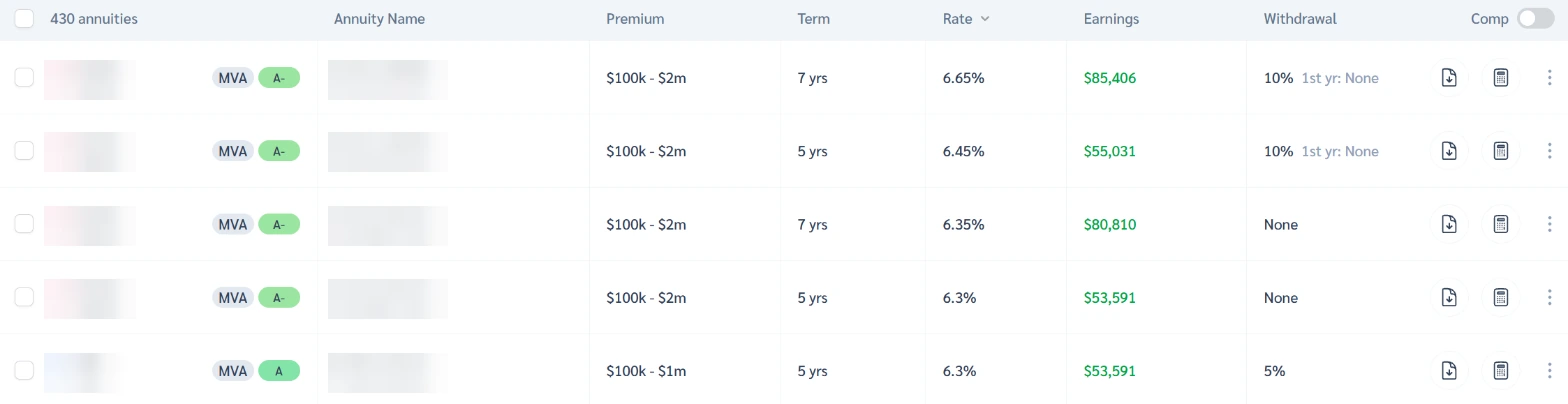
Practice Client, 3 Nov 2026: two 5-year rows pay 6.3%, earning $53,591 on $150,000. Withdrawal says None on one, 5% on the other.
Rates change every day, so yours will differ.
Open MYGAs in Genius (opens the app in a new tab)In the app: Marketplace → MYGAs
 (opens full size in a new tab)
-
1.
Put the client's CD rate beside the MYGA rows for the same Term. Read Rate and Earnings on their money.
Outside an IRA, CD interest is taxed yearly and MYGA gain when withdrawn. An IRA already defers tax either way.
-
2.
Read Withdrawal on each row. Two 5-year rows pay 6.3%, yet one says None and the other 5%.
- MVA
- Market value adjustment: a formula that can raise or lower what an early exit pays, as rates change.
Leaving early above any free amount may cost a surrender charge, and an MVA if tagged. Know the surrender-free date.
-
3.
With the client open, go to Calculators, Simulator. Click Add Scenario, Fixed Interest, then Simulate on a 6.2% row.
Portfolio ended at age 81, $267,631 withdrawn. The run held 6.2% past year 7: a hypothetical, not a product result.
 (opens full size in a new tab)
-
4.
Ask what the CD money is for. Then ask the insurer what happens at term end: renewal terms and minimum rate.
A bank CD has federal deposit insurance (FDIC) within its limits. A MYGA does not: the insurer backs it.
Sources
- Annuities Genius help: Fixed Annuities vs. MYGAs
- Annuities Genius help: Annuity Navigator, MYGA
- Annuities Genius help: The Retirement Simulator
- Annuities Genius help: Fee-based vs. commission-based annuities
- NAIC: Buyer's Guide to Fixed Deferred Annuities
- FDIC: deposit insurance
- IRS Publication 550: investment income
- 26 U.S.C. 72: taxation of annuities
- NAIC Model 570: advertisements of annuities
- Investor.gov: annuities
- Annuities Genius app, checked 3 Nov 2026