
Lesson 3 of 14 · Part 4 of 7
Check the fit, or say a clear no
An annuity must solve a named problem. Run four checks before any product, and say no when they fail.
Do it in Genius
All cases your client GrantAI More Income gap planning
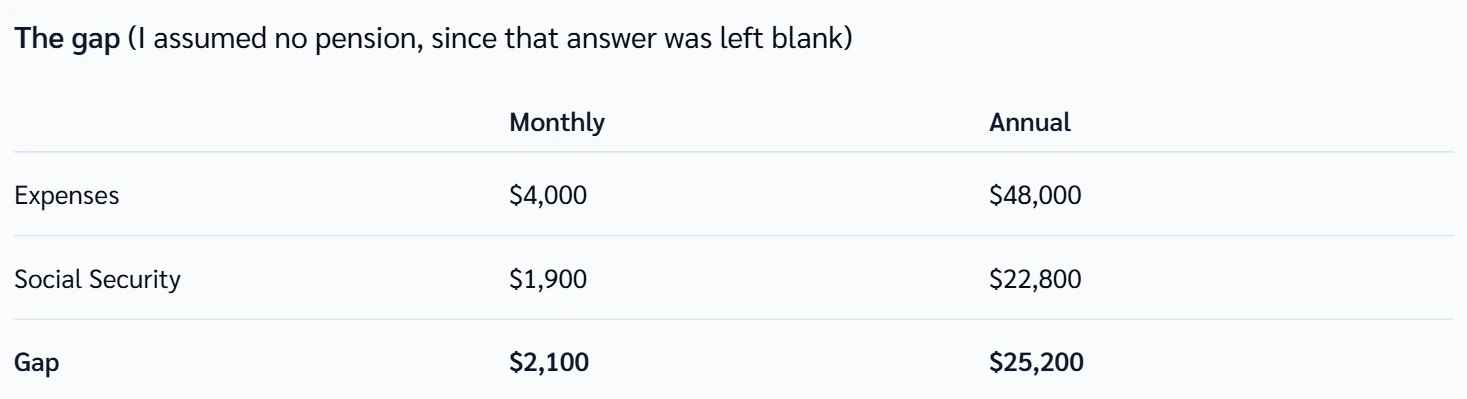
Practice Client, 3 Nov 2026: typed in $4,000 spending and $1,900 Social Security. The gap is $2,100 a month, $25,200 a year.
Rates change every day, so yours will differ.
Open your clients in Genius (opens the app in a new tab)In the app: CRM → All cases
 (opens full size in a new tab)
-
1.
Check what stays within reach: emergency cash, and how much is already in annuities. High-interest debt? Suggest they talk to their planner first.
GrantAI uses a six-month rule from insurers: 6 times $4,000 spending is $24,000. Insurers differ.
-
2.
Do the sum. Ask GrantAI: More, Income gap planning. Answer its four questions: spending, Social Security, other income, savings.
Type 0 for none. A blank answer may be saved as "No answer" and read as no pension. Read how GrantAI saved each one.
-
3.
Read What the IRA can fill from age 68. Compare the income rider, the deferred income annuity (DIA) and the immediate one (SPIA).
- DIA
- Deferred income annuity: money goes in now, and the paycheck starts more than about a year later.
- SPIA
- Single premium immediate annuity: one payment in, and a paycheck starts soon after.
For the Practice Client the verdict is part: the IRA alone cannot close the gap. The rider's calculator income is $15,810 of the $25,200 a year and it keeps access. The deferred one has no access.
-
4.
Read the bridge years, the two before 68. GrantAI first found $50,400 to cover and only $40,000 outside the IRA.
With the transcript saved, GrantAI drops this problem: she works until 68. Then say yes, part or no.