
Lesson 6 of 14 · Part 2 of 6
Read the index card, and say it in plain words
A fixed index annuity (FIA) applies a crediting formula to the index change. Cap, participation rate, spread or trigger shape the result. The credit is commonly floored at 0%.
Do it in Genius
FIAs row
Practice Client, 3 Nov 2026: the FIA list shows 493 annuities. One row shows 7 surrender years, an MVA tag and 27 allocation options.
Open FIAs in Genius (opens the app in a new tab)In the app: Marketplace → FIAs
-
1.
Read one FIA row before you speak: its surrender years, its tags, and how its best strategy earns.
- Surrender-charge period
- Years when a withdrawal above the free amount can cost a declining charge. An MVA, rider effects or tax may add more.
Sorting by Rate of return lifts young indexes, worked out from past data. 25.63% is not a promise.
See also:
-
2.
On the client's card, ask GrantAI the prompt below. Use its wording, not its product pick: it may name a Fee-based one.
- Cap
- The most interest the client can earn in a period, however well the index does.
- Participation rate
- The percentage applied to the index change. It is not a share invested in the index, and it can exceed 100%.
- Spread
- A set percentage taken off a gain before it is credited. A small gain can credit nothing.
- Trigger rate
- A set rate credited if the index is flat or up, under contract rules. Otherwise zero. It is not the index return.
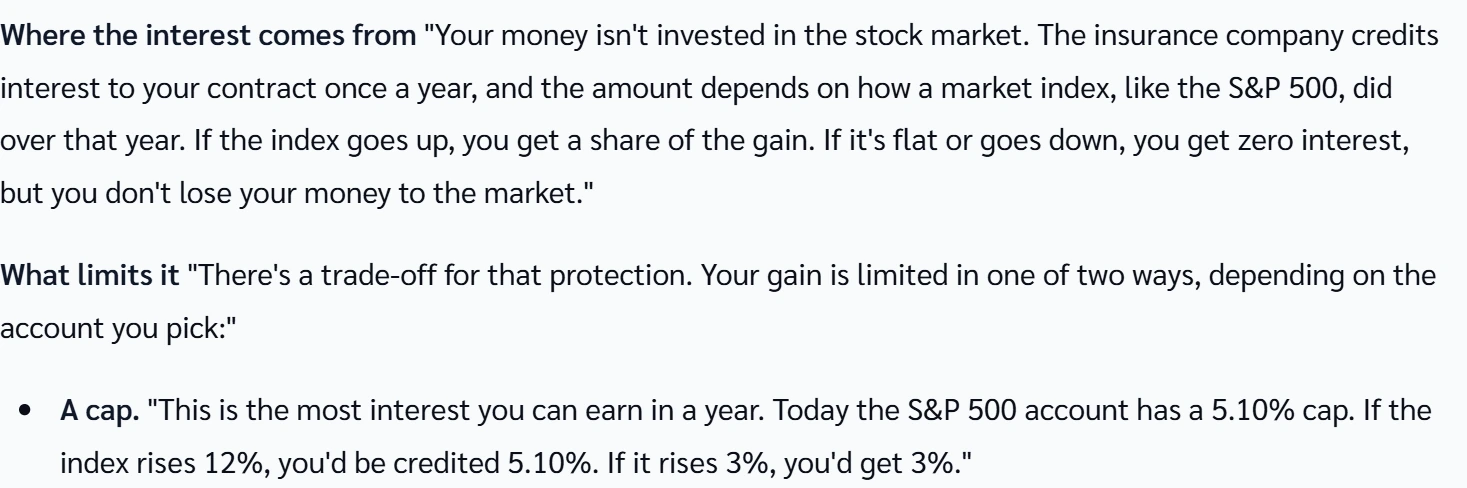
In plain words I can use with this client, explain where the interest in a fixed index annuity comes from and what limits it.
Select the text and copy it.
GrantAI's answer: the S&P 500 account had a 5.10% cap. A 12% rise credits 5.10%. A 3% rise credits 3%.
 (opens full size in a new tab)
-
3.
Add three more limits to check in this product's terms: dividends, renewals and fees.
A price index leaves out dividends. Total-return and custom indexes differ. Rates may reset each crediting period, within contract limits.
Sources
- Annuities Genius help: Filters Under the FIA Marketplace
- Annuities Genius help: Cap, Spread and Participation Rate
- Annuities Genius help: Growth/Accumulation Annuities
- Annuities Genius help: Renewal Rates
- NAIC: Buyer's Guide for Deferred Annuities
- Investor.gov: indexed annuities bulletin
- Annuities Genius app, checked 3 Nov 2026