
Lesson 5 of 14 · Part 6 of 10
Put an income annuity next to the rider
A SPIA (single premium immediate annuity) or DIA (deferred income annuity) turns a lump sum into a paycheck. Usually there is no way back. Quote one beside the rider.
Do it in Genius
SPIA calculator Premium & Income Income Start Date Make it a QLAC Get quotes
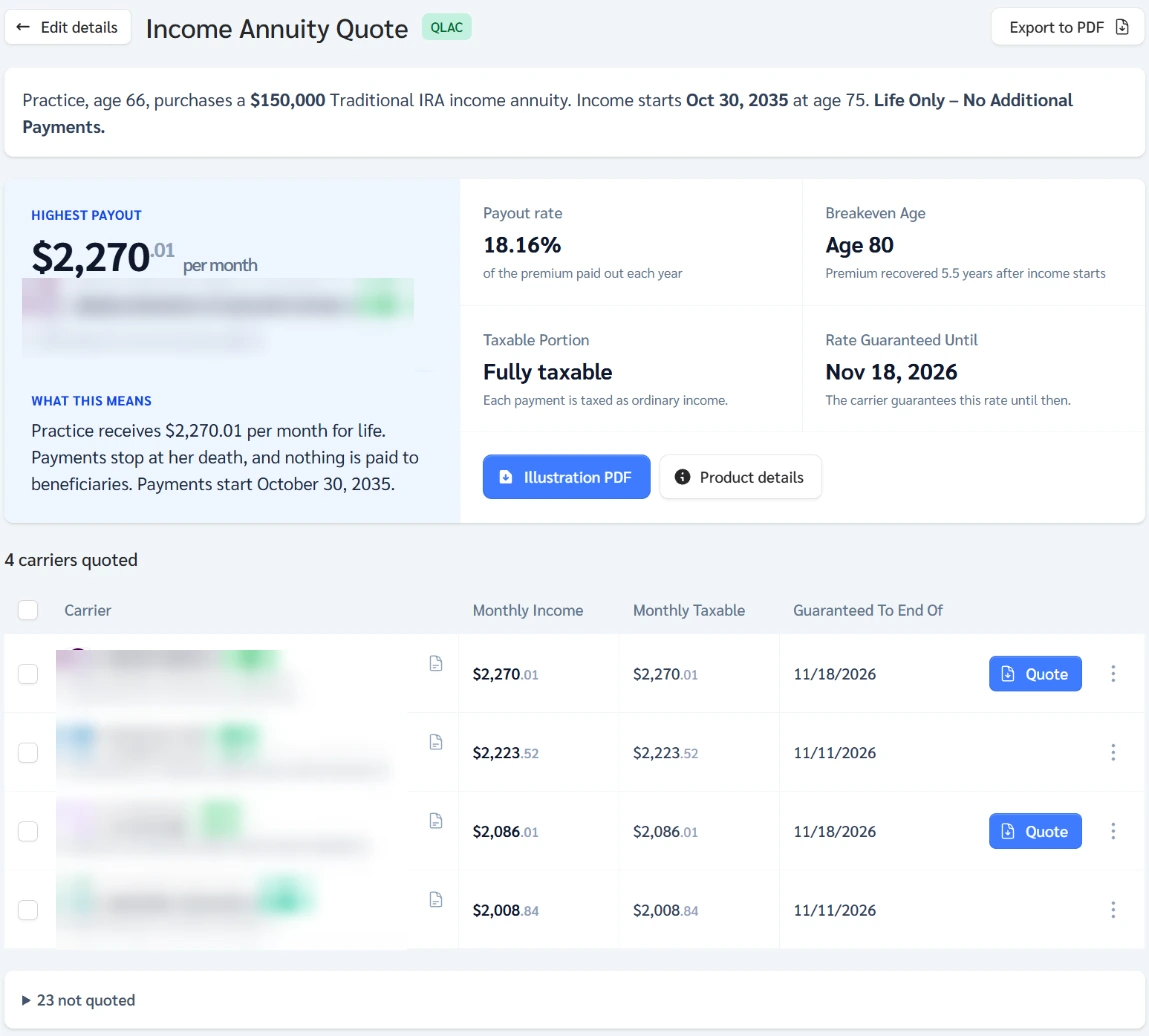
Practice Client, 3 Nov 2026: a deferred IRA income (QLAC) from age 75 pays $2,270.01 a month. Breakeven Age is 80.
Rates change every day, so yours will differ.
Open SPIA calculator in Genius (opens the app in a new tab)In the app: Calculators → SPIA calculator
 (opens full size in a new tab)
-
1.
Open SPIA calculator. Under Annuitants, pick the lives and check the Date of Birth. Under Premium & Income, type the premium.
A quote needs a birth date. For the Practice Client it filled in 10/30/1960: check it with the client.
-
2.
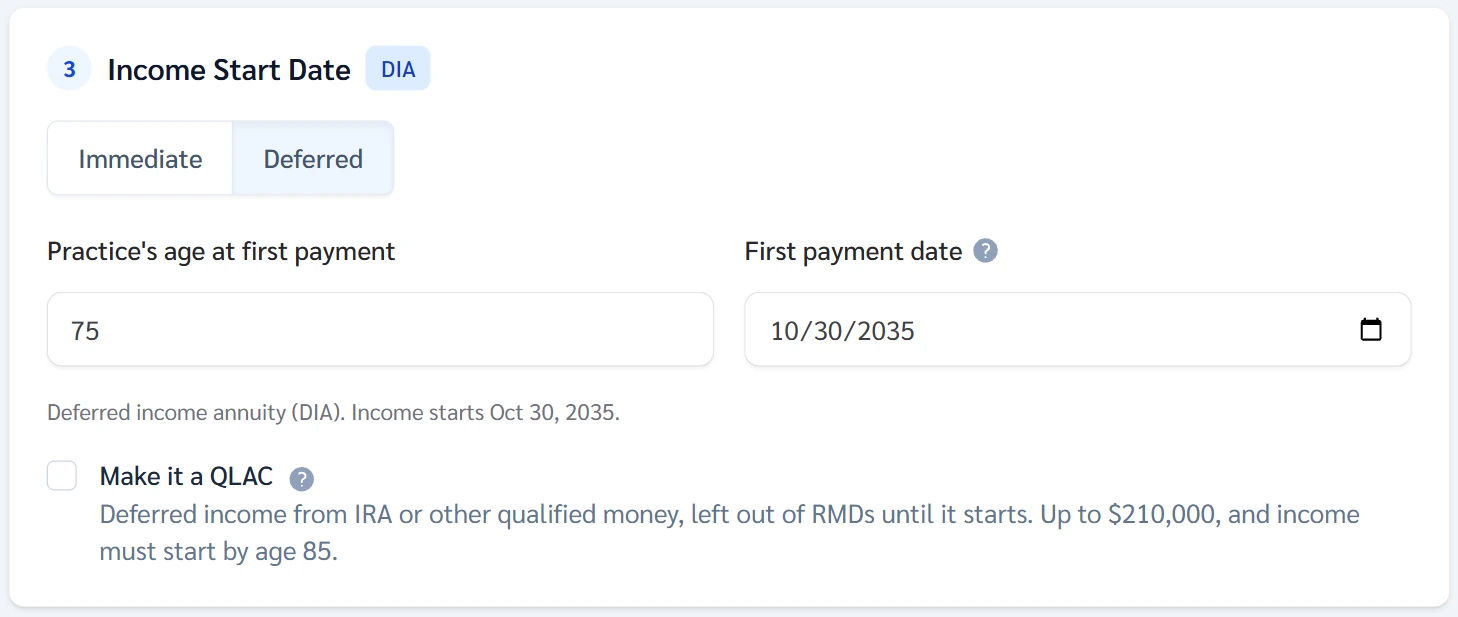
Set Source of Funds. Under Income Start Date, pick Immediate or Deferred, and set the age to the rider's start.
Deferred starts at 75 until you change it. Within 12 months it is a SPIA, later a DIA. Qualified means IRA or 401(k) money. The tax part explains it.
-
3.
With Deferred and Traditional IRA or other qualified money, tick Make it a QLAC. Roth IRA and non-qualified money can't be a QLAC.
- QLAC
- Deferred income bought with qualified money. If it meets QLAC rules, its value is excluded from the required-withdrawal balance until income starts. The 2026 premium limit is $210,000 per person.
Her required withdrawals start at 75, so a QLAC starting at 75 defers nothing. Its value stays out of that balance only until income starts: quote a later age, up to 85.
 (opens full size in a new tab)
-
4.
Pick a Payout Option: what happens if the client dies early. Click Get quotes. Put the top income beside the rider's $1,318 a month.
- Life Only
- Payments stop at death. Nothing goes to the family. The highest income.
- Life with Refund
- If the client dies early, the unpaid part of the premium goes to the beneficiaries.
- Life with Period Certain
- Payments last at least the years you set, even if the client dies.
Like with like: set the age to 68, the rider's start, and untick Make it a QLAC for a DIA. The rider's $1,318 is the calculator figure: confirm it in the illustration. The rider lets 10% a year out free, and a life-only income annuity has no account.
Sources
- Annuities Genius help: SPIA/DIA Calculator
- Annuities Genius help: How to use the SPIA (and DIA) Calculator
- Annuities Genius help: Annuity Marketplace (Types of Annuities)
- Annuities Genius help: How to Choose the Right Annuity
- IRS: Required minimum distributions
- Annuities Genius app, checked 3 Nov 2026
- IRS: Form 1098-Q instructions, QLAC rules
- Treasury rule: a QLAC is left out of the RMD balance, 26 CFR 1.401(a)(9)-5(b)(4)