
Lesson 6 of 14 · Part 5 of 6
Present growth money as a ladder
Nobody knows where rates go. A ladder splits the money across terms, so some of it comes due every few years.
Do it in Genius
All cases your client GrantAI More Annuity laddering strategy
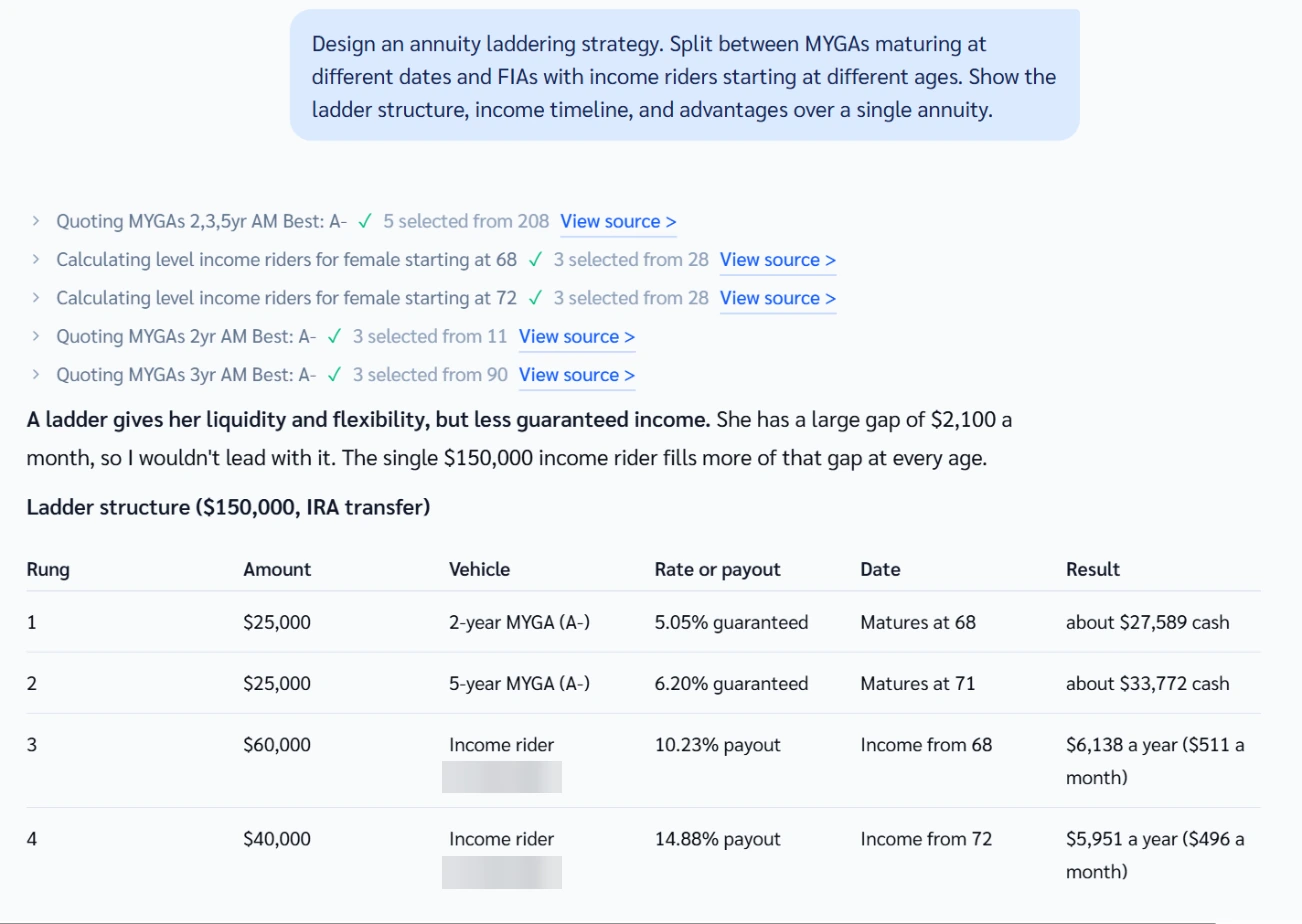
Practice Client, 3 Nov 2026: GrantAI split $150,000 into four rungs. Rungs 1 and 2 are $25,000 MYGA contracts at 5.05% and 6.20%.
Rates change every day, so yours will differ.
Open your clients in Genius (opens the app in a new tab)In the app: CRM → All cases
 (opens full size in a new tab)
-
1.
Run Annuity laddering strategy in More and wait about 90 seconds. Read rungs 1 and 2.
Two $25,000 MYGA terms end at ages 68 and 71, with about $27,589 and $33,772 in cash.
-
2.
Check both rungs in the MYGA list: a 2-year row and a 5-year row, at today's rates.
GrantAI quoted 5.05% and 6.20% on 11/3/2026. Verify each contract's surrender-free and renewal dates, and the carrier.
See also:
-
3.
Read rungs 3 and 4: a $60,000 rider paying 10.23% from 68, a $40,000 rider paying 14.88% from 72. Re-quote both.
GrantAI scaled both from $100,000 quotes. Rung 3's 10.23% payout is the Fee-based row: a commission agent swaps in a row they can sell.
-
4.
Compare the ladder with one $150,000 rider. GrantAI would lead with the rider here. Offer the ladder for a reserve or inheritance.
GrantAI says the single $150,000 rider fills more of the income gap at every age.